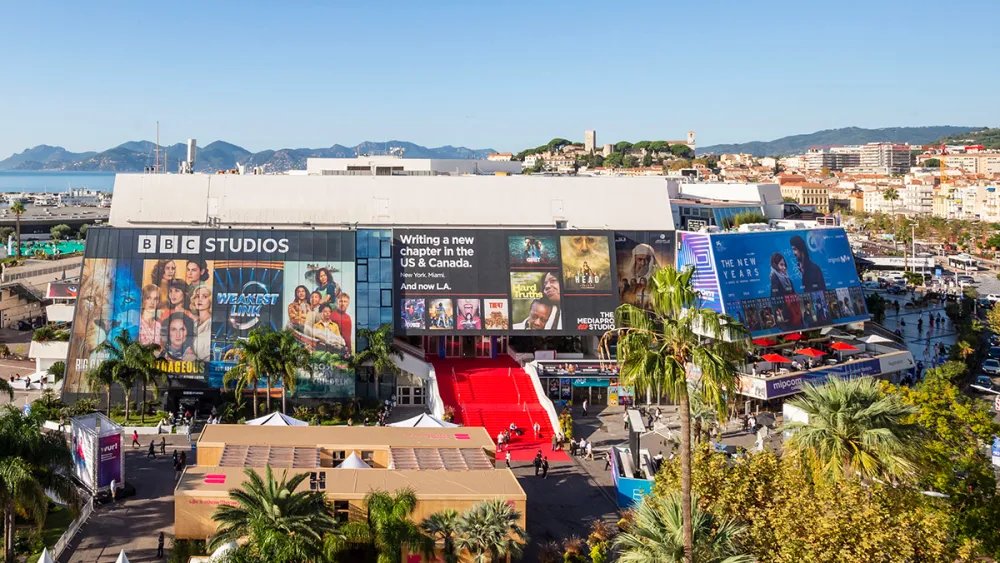
The biggest problem for a lot of children’s content creators these days is getting their series financed. Many are now at Mipcom, the world’s largest annual TV convention, starting Monday in Cannes, the same French Riviera city that hosts the famous film festival.
The proceedings began on Saturday with MipJunior, the children and family prologue to Mipcom.
In a brief but strong scene-setting snapshot of the 2026 kids content market that helped kick off MipJunior’s proceedings, Cyrene Amor, senior research manager at Ampere Analysis, reveals the decline in streamer orders over the past four years, and why.
Plunging Streamer Order
In the last decade, new streaming services were seen as a great hope for the children’s and family entertainment industry. Parents may not want to shut down a service that provides their children’s favorite TV shows; Children like to watch again and again, the argument went.
10 years later, orders for the streaming service’s first run have declined sharply. Orders for SVOD service Kids TV fell from 196 in the 12 months to 1H2022 to 88 over the 12 months. Amor said this represents a 22% increase compared to the 2025 figure of 72. But it comes from a fundamentally lower base.
biggest competition
What happened? First, children’s entertainment is now available on many new platforms. Amor said in the presentation that SVOD operators stream 240,000 hours of content annually globally, with Netflix alone 4,000 hours. Yet AVOD provides 140,000 hours per year worldwide, Tubi only 24,000. And YouTube has 250 kids’ channels with over 10 million subscribers and a total of 300,000 hours of videos, shorts, and livestreams, 80% of which are pre-school channels.
Plus, streaming audiences are focusing on the goldie-oldies
Additionally – and this is true for mass audiences for series and movies – streaming services have found that the majority of their viewing is long tail, accounting for an astonishing 90% of views and 75% of titles, according to Ampere Analysis’ Plumresearch. Think “Star Trek,” “Dark,” “Archer” and “Primal,” not to mention first-run hits like “Squid Game.” SVOD operators have responded. The share of “new content” hours (released for the first time during the last five years) on Amazon Prime Video is set to decline from 22% in July 2022 to 11% in July 2024. Disney has dropped from 23% to 13% over the same time period. Netflix has made a big effort to offer first run commissions. Yet its share of new content has fallen from 48% to 36%.
General Alpha likes video games
Compounding matters, it’s not clear that Gen Alpha is primarily interested in streaming services, even YouTube. Gen Z has different needs stateside, Amor said, with different primary media services when it comes to four of the six most important of them — “when I’m bored”; “Want to drown”; “Wanting to discover something new” and “wanting to take their mind off things” – Gen Z turns to streaming services. Yet for Gen Alpha, born between 2010 and early 2020, streaming services or YouTube are the only two options to consider. When the General Alpha wants to drown, or take his mind off things, or is bored, he will turn to video games or game apps.
big picture
Netflix Animation executives are passionate and experienced in their work. But he has never signed up to the bottom line of becoming a savior of anything. And why should they do this? They are a private sector business. This role is that of public service broadcasters who have a brief to ensure educational children’s entertainment.
Here, although Mipjunior begins blessed with early autumn sun, the landscape is cloudy.
The BBC and Germany’s ARD such as PBS pride themselves as the largest sources of first-run orders for children’s content, having made 371 commissions in the 12 months to the first half of 2026. Evan Shapiro, who gives the valedictory address at MJunior on October 11, once said, “Public service media should be valued.” Tea
The bad news: The public broadcaster’s revenues have stagnated, Amor said, with revenues projected at $53 billion in 2026. That’s down from $174 billion for subscription OTT and $292 billion for other online advertising revenues in 2026, Amor said.
The inflation factor, currently at 3.8% in the EU, is declining and public broadcaster revenues are declining. They are also an easy target for future broadcaster budget cuts.